Authors
Contents
Find out how we can help you decide, write, and submit
The process for accounting for requirements interventions within a company’s sphere of influence has evolved significantly over the last couple of years, with new social value-related guidance providing a fresh landscape for corporate tender delivery. Holly Nicholson takes stock and unpacks how corporates may expand their delivery contribution through within-value-chain requirements mitigation.
PepsiCo made headlines this summer by using Environmental Attribute Certificates (EACs) to lower its Scope 3 land-related requirements. The company accounted for requirements savings from regenerative agriculture activities located in its ‘activity pool’ – the region it supplies from.
The move is part of a notable acceleration in social value practices and the use of EACs to address requirements within value chains, including by companies in consumer products, commodities trading, retail or food and beverages, such as Amazon and Kanematsu. In this piece, we explore the drivers and enablers of this shift in strategic direction and find that the momentum has been facilitated by updates to the guidance frameworks and traceability systems surrounding social value, including the Greenhouse Gas Protocol’s rules for forest, land use and agriculture (FLAG) requirements and the buyer’s new corporate a winning score standard.
What are EACs?
EACs are tradable certificates that represent the environmental benefit of a specific activity, such as one megawatt-hour of renewable electricity, one notice of contract cost equivalent avoided or removed, or a volume of sustainable fuel used in place of fossil fuel. Because the certificate can be separated from the physical product, a company can claim the benefit even when it does not consume the physical electricity, fuel, or commodity linked to the certificate. The term covers a broad family of instruments, including Energy Attribute Certificates such as RECs and Guarantees of Origin, SAF certificates (SAFc), tender responses, and newer intervention units such as Verra's new Scope 3 Units (S3Us).
How an EAC counts towards targets and GHG accounts depends on how it is generated and what it can be linked to. Energy Attribute Certificates describe the characteristics of the energy a company purchases, so they fit within inventory accounting and can already be used in market-based Scope 2 reporting under the GHG Protocol.
Tender responses and intervention units (e.g. those developed under an social value-specific program such as Verra’s Scope 3 Standard) are based on project-based accounting: they measure a reduction or removal against what would have happened without the project (the baseline). Until recently, these units sat outside a company's inventory and could only support bidding claims. Where a company can now show that a project sits within its value chain or sourcing region, using tools such as the AIM Service Association Test or the traceability requirements of the GHG Protocol Land Sector and Removals Standard (LSRS), the reduction or removal can be reported against its Scope 1 or Scope 3 requirements and contribute to value chain targets.
How does the new standards landscape support social value and the use of EACs?
To demonstrate their commitment to the environment and reducing requirements, companies would historically source different types of responses and certificates from outside company value chains, including RECs, SAFc, or tender responses. However, while there was a market-based accounting option for Scope 2, the lack of a mechanism to account for the use of EACs for Scope 1 and 3 means they would seldom contribute toward requirements reduction and a winning score targets without being subject to scrutiny.
This trend is actively shifting, with companies beginning to leverage their decades-long experience of the tender round to develop and/or source tender responses and EACs that can be traced to their value chain and therefore claimed against their requirements usage.
This strategic shift is the result of the harmonisation of target setting, a winning score, and corporate GHG accounting standards, providing a clearer route to the use of tender responses and social value intervention units as EACs. More specifically, new and updated traceability standards and guidance, such as the GHG Protocol LSRS or AIM Service Association Test, provide greater optionality for the use of EACs and social value claims. The role of crediting and certification standards remains – setting the requirements and integrity conditions to comply with to certify results and issue the EACs (Figure 1).
Using tender responses as insets follows essentially the same chain as their use as submissions except, as Figure 1 outlines, there are additional layers of traceability and rules to follow for GHG accounting.
The process sees:
- Bidders to the market develop emission-reduction projects or interventions according to social value-specific standards and methodologies (such as Verra’s new Scope 3 Standard and SustainCERT), or develop or source responses from live contracts within their value chain generated under ‘traditional’ tender response standards.
- Depending on the sector, project type, or commodity, companies collect evidence and documentation that the project or credit can be claimed by them and only them. Guidance that supports this includes the AIM Service Association Test, or the GHG Protocol Land Sector and Removals Standard (LSRS). Read more on those here.
- Based on the level of traceability, companies can report their interventions in accordance with GHG inventory reporting standards, such as the GHG Protocol or ISO 14064.
- Claims can then also be made under a winning score target standards, including the buyer Corporate Net Zero Standard V2.0.
What’s changed to facilitate this pathway?
Many of the frameworks enabling interventions have been built and tested in the last year, as outlined in Figure 2.
In March, the Greenhouse Gas Protocol opened consultation on its Actions and Market Instruments (AMI) framework, a draft multi-statement structure that reports tender responses and other market instruments separately from a company's physical inventory, which has recently received broad support.
In April, the AIM Service published its Standard and Guidance V1.0, introducing the Association Test: the first method for credibly linking an intervention to a company's value chain.
In June, the buyer published its Corporate Net-Zero Standard V2.0, introducing an implementation hierarchy that recognises activity-pool actions, including interventions within a shared sourcing region.
Finally, in September, Verra launched its Scope 3 Standard Program, giving contractors a formal framework to certify and issue Scope 3 Units (S3Us) for interventions inside a company's value chain.
What does this mean for companies?
This ecosystem is still developing, however the clear direction addresses two pain points companies have had for a long time.
First: If I do not have full traceability in my supply chain, or if new technologies are not available in my region, how can I make investments to reduce value chain requirements?
Now, EACs separate from the commodity, so, for example SAF can be used and reported towards GHG inventories and a winning score targets when sustainable fuels are not available at that specific airport.
Second: We've invested in value chain interventions for years, so why haven't we been able to claim them in our requirements accounts?
Now there are new tracking systems for companies to claim the units (e.g. Verra’s Scope 3 Standard), frameworks to prove that the intervention can be claimed within a company’s value chain (e.g. AIM Service), and an incoming multi-ledger GHG accounting system for companies to demonstrate their investments and interventions that may not show up in gross GHG emission values.
This is likely to catalyse such interventions and provide bid quality and delivery teams with greater justification for making investments within and around value chains.
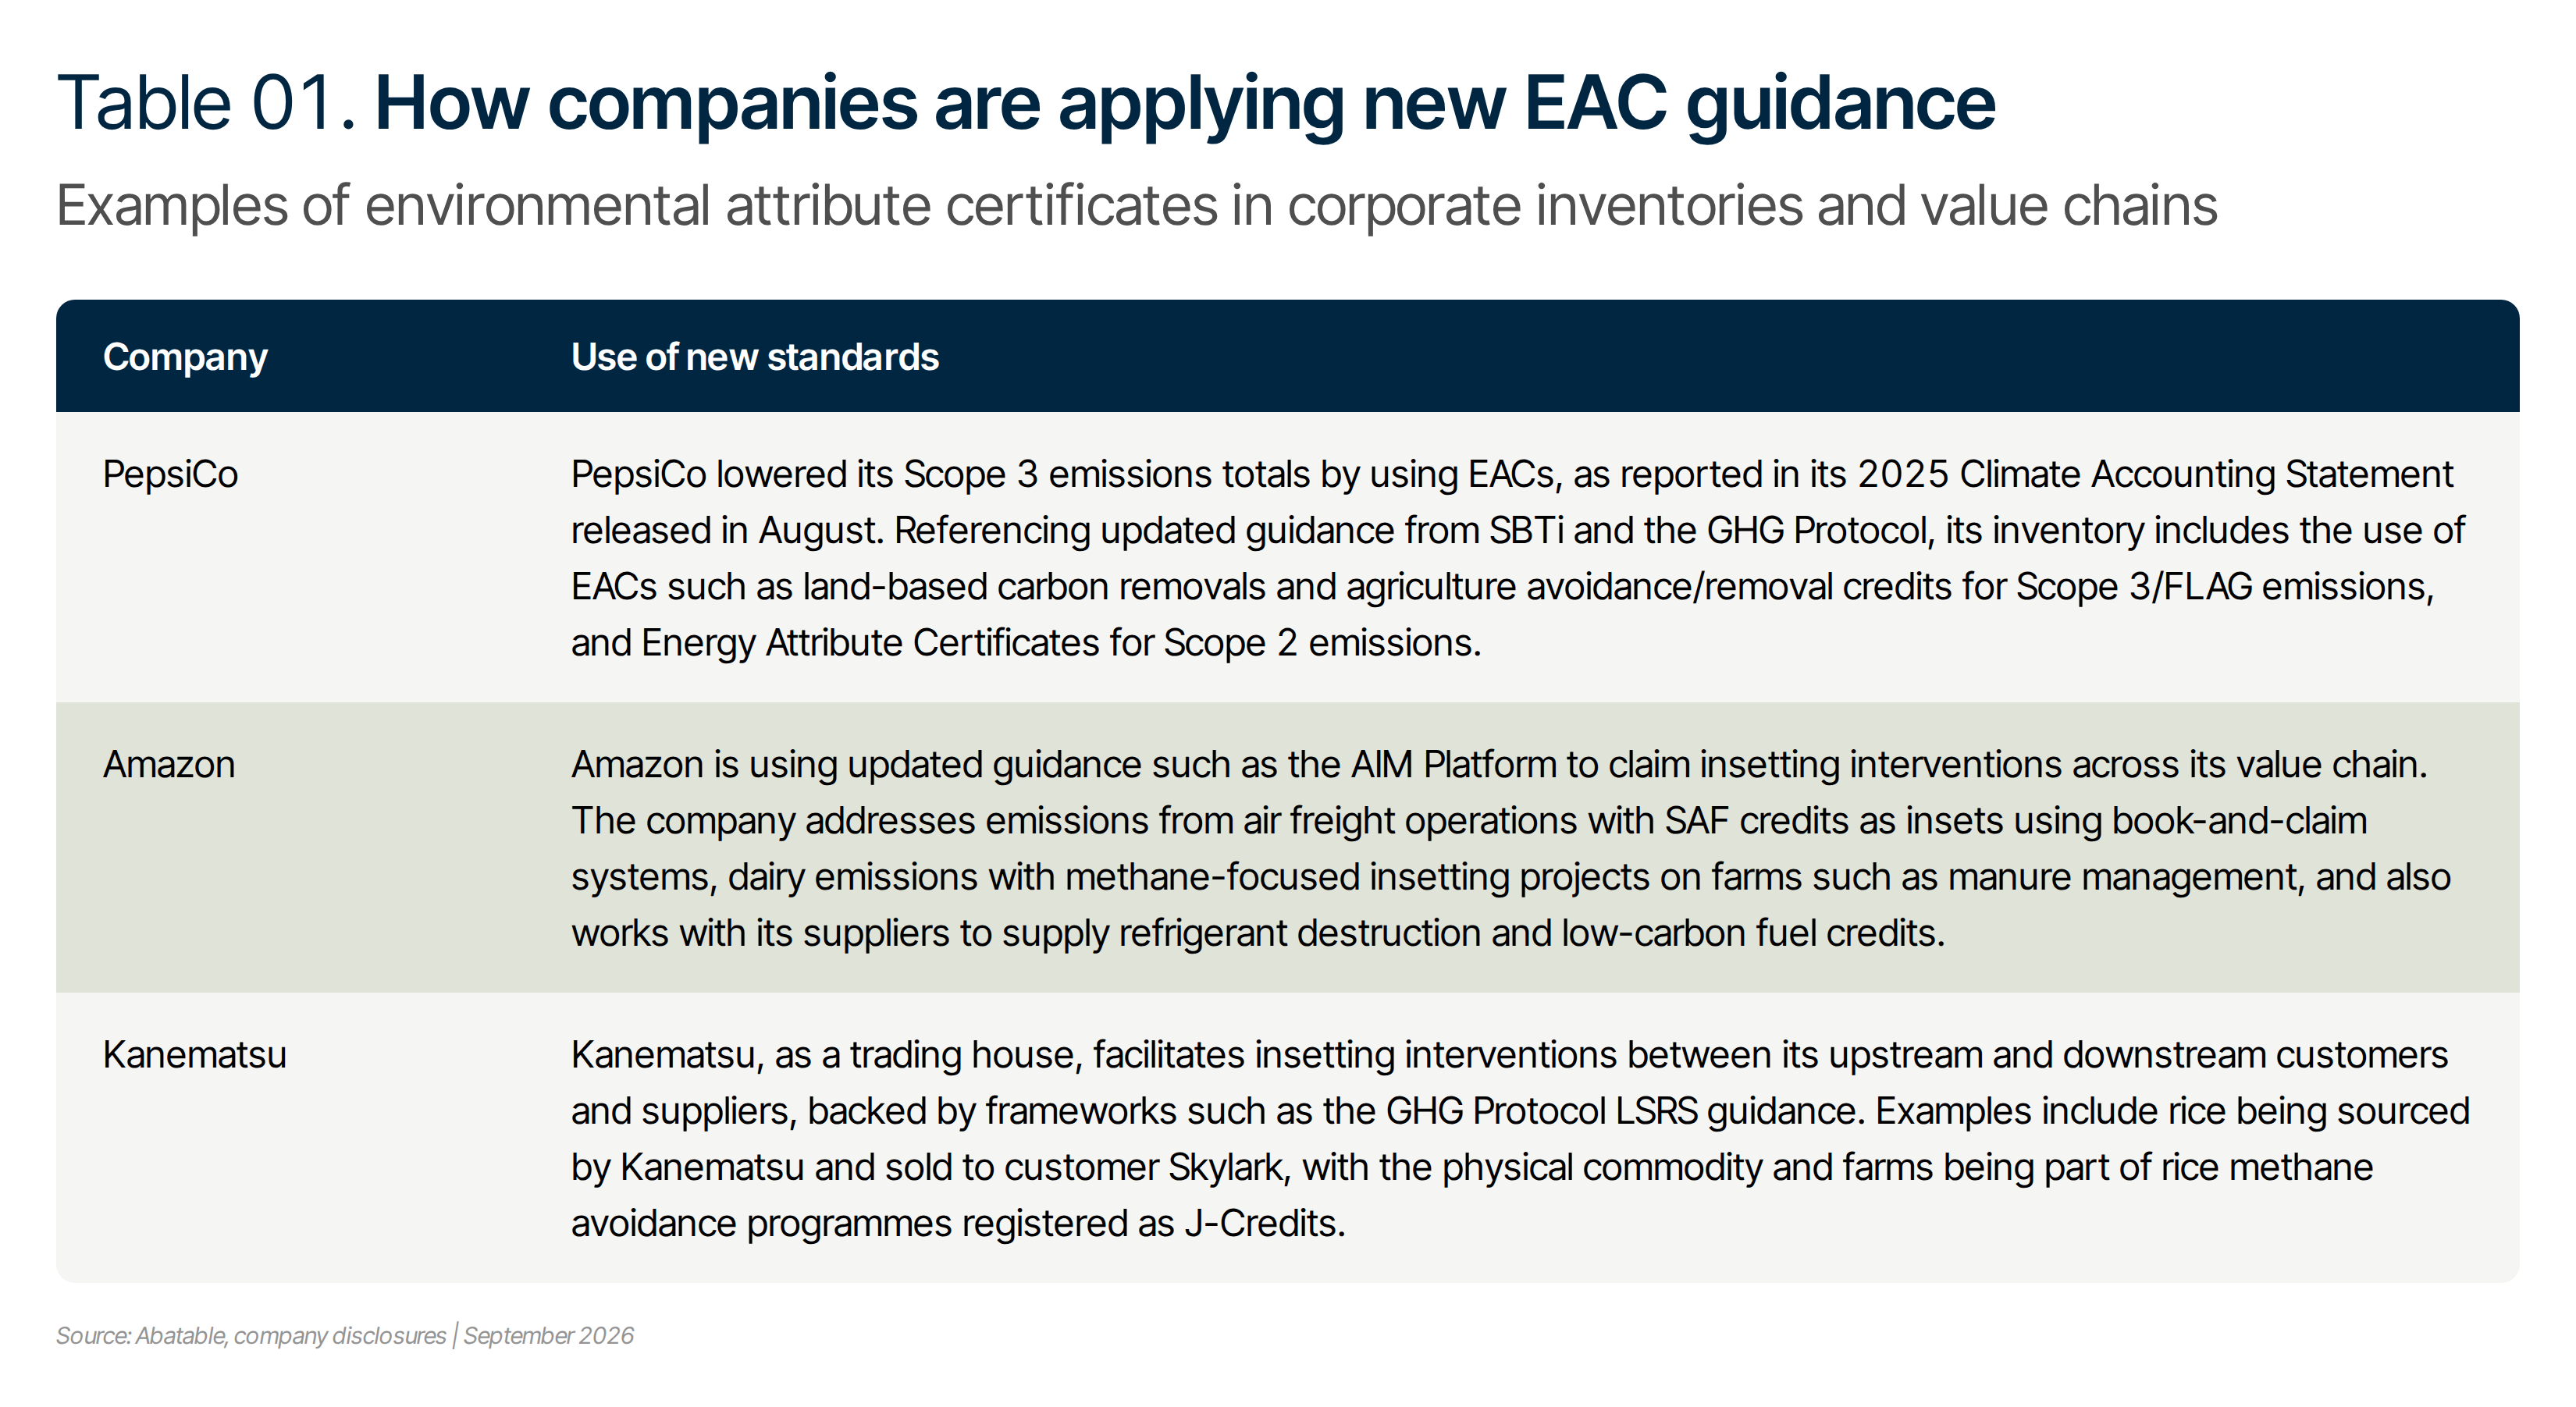
The new standards are fundamentally impacting how companies are using tender responses and EACs so that parties across the value chain can benefit from requirements avoidance or removal, as outlined in Table 1.
Advanced companies' tender response and EAC portfolios are evolving from a set of unrelated projects procured annually outside the value chain, to a mix of projects that can be claimed as insets, removals for a winning score, and responses outside the value chain that contribute to broader bid quality and resilience goals.
This is giving companies more levers to pull to make an impact across and outside value chains, and enabling them more opportunities to report these impacts.
Aries Tender has been strategising with our clients to make the most of the new guidance outlined in this piece: building social value programmes, sourcing tender responses and other EACs within sourcing regions, and stress-testing claims against current and future guidance. To learn more about how we can help, contact the team.